Acquisition Funding Leeds: The 2026 Strategic Guide to Deal Financing
The most successful acquisitions in 2026 are won in the data room, not at the negotiation table. With the Bank of England base rate holding at 3.75%, the margin for structural error has disappeared. You likely feel the friction. Traditional debt is expensive. Lenders are cautious. Securing acquisition funding Leeds now requires more than a solid balance sheet; it demands a deal structure that accounts for high interest rates and the 25% corporate tax rate on profits over £250,000. Slow due diligence and sector-specific hurdles in manufacturing or tech only add to the pressure.
This guide provides the strategic roadmap you need to navigate these complexities. You'll discover how to leverage alternative finance and seller-led structures to bridge the gap left by high-street banks. We'll show you how to prepare your transaction to attract capital and manage the process with precision. From optimizing your data room to securing investor confidence, this is your framework for a successful Leeds acquisition. Funding follows structure. We help you build it.
Key Takeaways
- Identify why the Leeds manufacturing and tech sectors require specific funding structures to navigate the 2026 economic landscape.
- Navigate the "Capital Stack" to secure acquisition funding Leeds, balancing debt, equity, and mezzanine finance for maximum deal stability.
- Reduce dependence on traditional commercial loans by integrating seller financing and vendor take-back options into your deal structure.
- Build a professional funding pack that prioritises verified business valuation reports to accelerate lender approval and investor interest.
- Use the SellAnyBiz.com acquisition workspace to centralise your transaction, from AI-powered search to secure due diligence management.
Table of Contents
Navigating the Acquisition Funding Landscape in Leeds
Leeds serves as the commercial heart of the Northern Powerhouse. It's a city defined by transaction volume and sector diversity. Manufacturing, professional services, and healthcare dominate the local landscape. These industries attract consistent deal flow. For buyers, the challenge isn't finding targets; it's securing the capital to close. Acquisition funding is a blend of capital sources used to purchase an existing entity. In the West Yorkshire market, this requires a sophisticated approach to the capital stack. Securing acquisition funding Leeds involves navigating a network of regional debt providers, alternative lenders, and private equity firms.
Local West Yorkshire advisory firms play a critical role. They bridge the gap between buyer intent and lender requirements. These professionals understand the nuances of the regional economy. They know which lenders have an appetite for Leeds-based manufacturing and which prefer tech-heavy service firms. In Q1 2026 alone, the UK saw 352 mergers and acquisitions. A significant portion of this domestic activity centered on regional hubs like Leeds. Success in this environment starts with understanding mergers and acquisitions from a localized perspective. Buyers must align their funding requests with the specific economic realities of the North.
The Leeds Economic Advantage for Buyers
Leeds offers a mature professional ecosystem. Infrastructure is robust. The pool of mid-market targets is deep. Regional investment funds often prioritize businesses within the West Yorkshire boundary. This local preference creates a competitive advantage for buyers who can demonstrate a commitment to the region. Many investors look for "Northern-centric" portfolios. They value the resilience of the local workforce. They see the growth in the digital and data sectors. Buyers using the SellAnyBiz.com platform often find that local targets come with established supply chains and loyal customer bases. This stability makes them attractive to lenders who are wary of volatility.
Current Market Sentiment in West Yorkshire
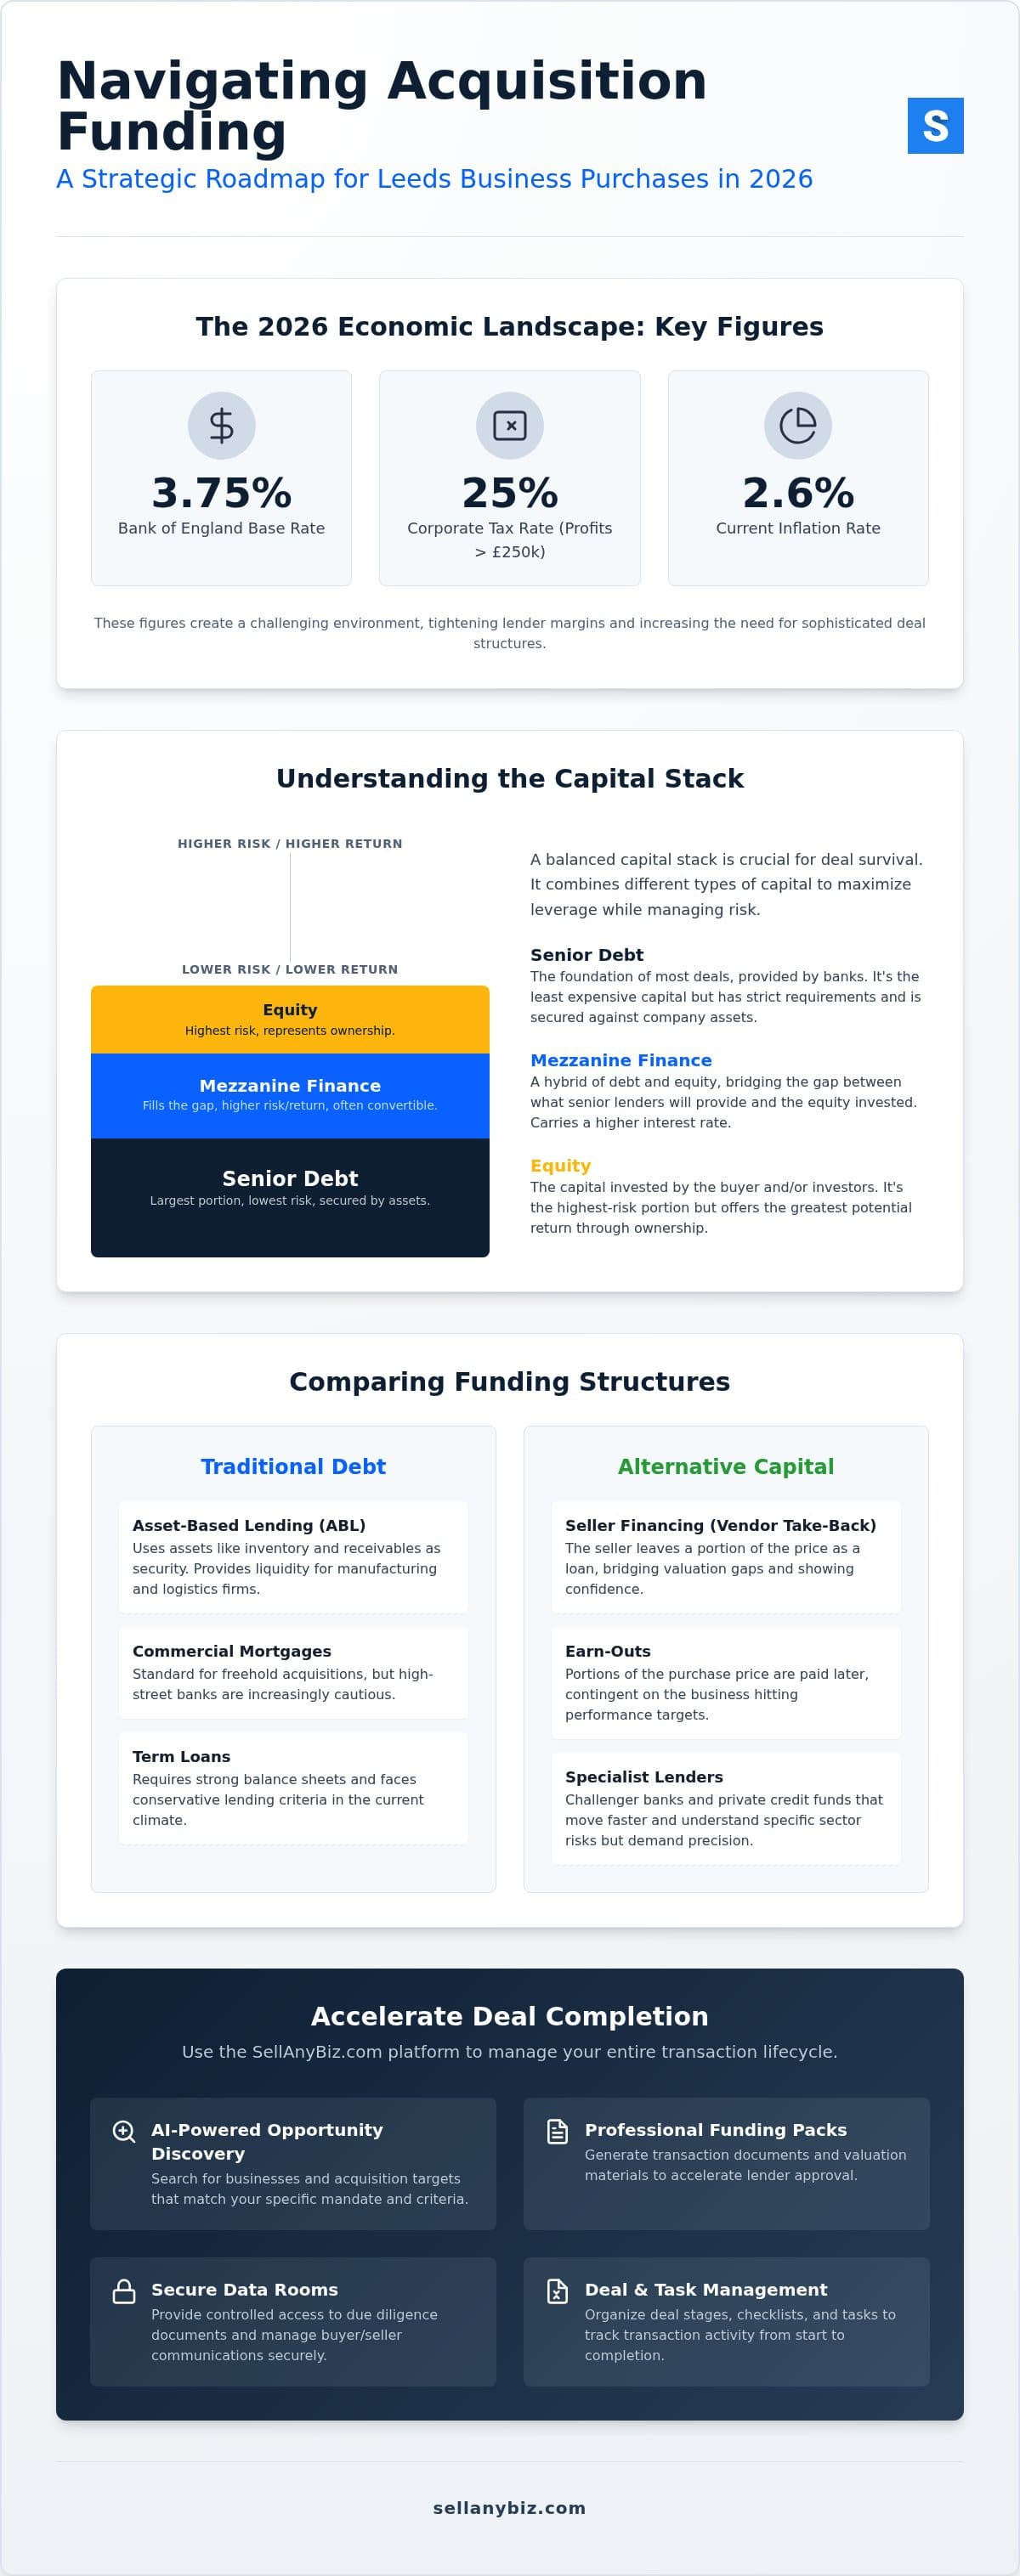
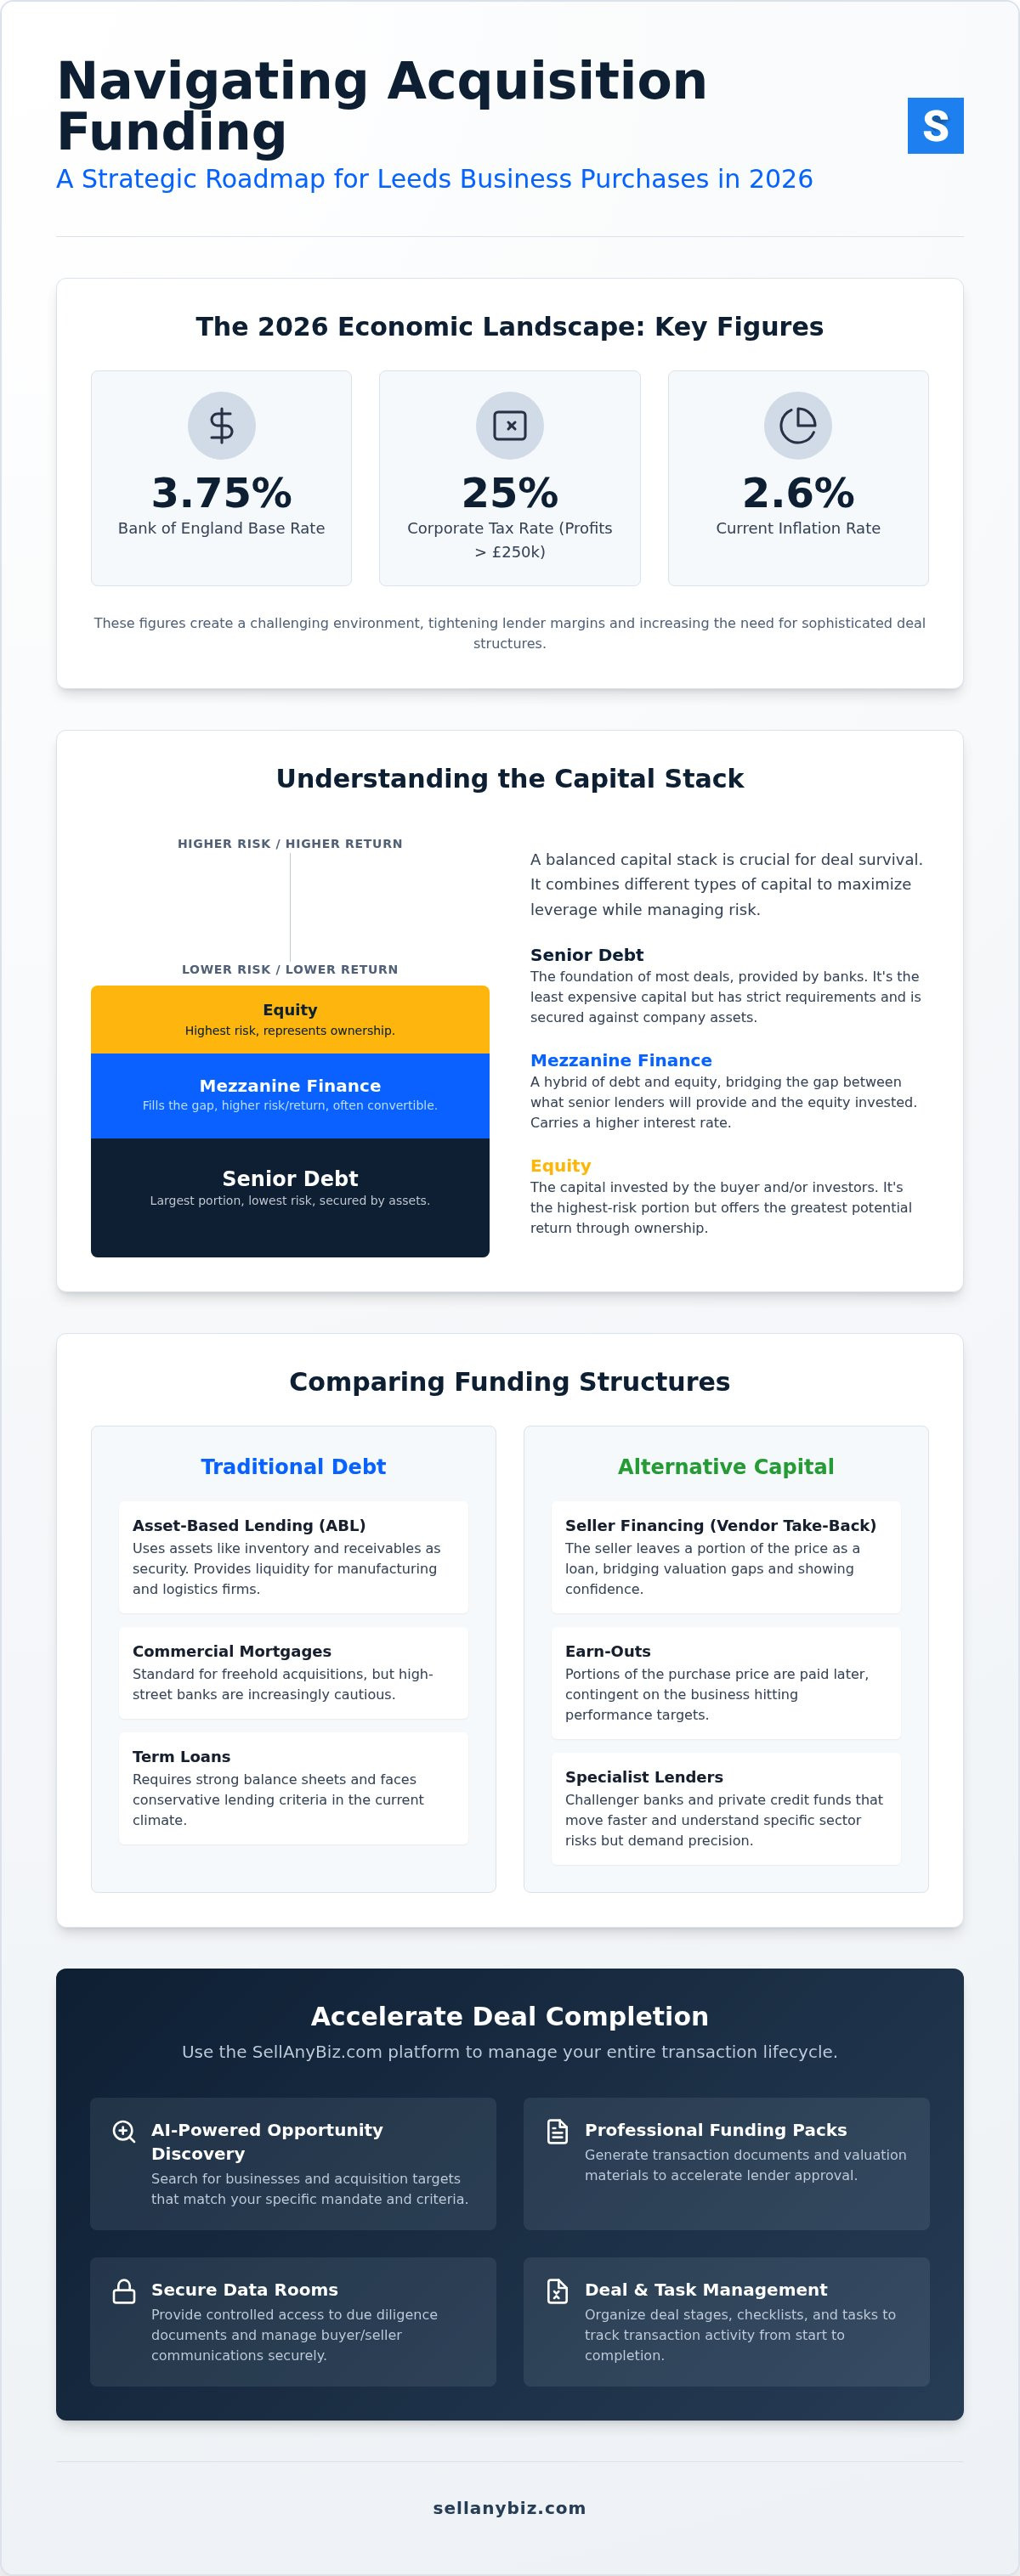
The 2026 economic climate is one of disciplined growth. The Bank of England base rate sits at 3.75%. Inflation is currently 2.6%. These figures have tightened lender margins. High-street banks have become more selective. They view brick-and-mortar risks through a conservative lens. This caution has created a "funding gap" for businesses valued between £500,000 and £5 million. Fiscal policy also weighs on deal structures. The 25% corporate tax rate for profits over £250,000 impacts how buyers calculate debt serviceability.
Specialist lenders and challenger banks are filling this void. They move faster than traditional institutions. They understand the specific operational risks in Leeds manufacturing. However, they demand precision. Verified data. Clean financials. A structured transition plan. Without a professional acquisition funding Leeds strategy, capital remains difficult to access. Buyers must present a deal that is not just viable, but bankable in a high-interest environment.
Primary Funding Structures for Leeds Business Purchases
Deal structure dictates deal survival. A balanced capital stack is essential. Debt. Equity. Mezzanine. Each has a specific role. In the current environment, securing acquisition funding Leeds often involves a mix of senior debt and alternative capital. Senior debt provides the foundation. Equity offers the risk buffer. Mezzanine finance fills the remaining gap. This tiered approach allows buyers to maximize leverage while managing repayment risks.
Manufacturing and logistics are Leeds staples. These firms often hold significant physical value. Asset-based lending (ABL) uses these assets as security. Plant. Machinery. Receivables. Inventory. It provides liquidity without the rigid constraints of a standard term loan. For freehold acquisitions, commercial mortgages remain the standard. However, smaller entries might benefit from government-backed loans. These often carry fixed rates, such as the 7.5% interest rate available for specific start-up initiatives. It's worth reviewing UK government business financing options to see which schemes align with your target sector.
Leveraging Seller Finance in 2026
Valuation gaps are common. Sellers expect historic prices. Buyers see 2026 risks. Seller finance bridges the divide. This is often called a "Vendor Take-Back." The seller leaves a portion of the purchase price in the business as a loan. This structure reduces the initial cash requirement. It also signals the seller's confidence in the firm's future. Earn-outs are a specific subset. These deferred payments depend on the business hitting performance targets post-sale. They protect the buyer's capital. If you want to find motivated sellers, you can browse Leeds business listings to see where these terms might fit.
Debt Financing Options for West Yorkshire Acquisitions
Traditional banks have deep roots in Leeds. They provide stability and lower costs. Their due diligence is often slow. Challenger banks and alternative lenders fill this void. They are agile. They offer bespoke terms for mid-market deals. These lenders often provide the speed required to close a competitive transaction.
The choice between fixed and floating rates is critical. The Bank of England base rate is currently 3.75%. Fixed rates provide a hedge against volatility. Floating rates offer flexibility. If rates drop to the projected 3.25% by late summer, floating debt becomes cheaper. Your decision should rest on cash flow resilience. High-leverage deals often require the certainty of a fixed rate. Low-leverage deals can afford to track the market. Successful acquisition funding Leeds requires matching the debt profile to the target's operating margins.
A well-structured deal is easier to fund. You can start by identifying targets that fit your criteria through our Leeds business marketplace.
Comparing Traditional Debt vs. Alternative Acquisition Capital
Capital is a tool. Its value depends on how you deploy it. In the Leeds market, the choice between traditional debt and alternative funding often determines the success of a bid. Banks offer the lowest cost of capital. They also impose the strictest covenants. Alternative lenders prioritise speed and execution. They move when banks hesitate. Understanding the trade-offs between cost, control, and speed is essential for any serious buyer seeking acquisition funding Leeds.
Private equity is the right choice when the acquisition requires a massive scale-up that debt cannot support. It brings expertise but requires a significant portion of the equity. For smaller, entrepreneurial deals, search funds are gaining traction in West Yorkshire. They provide a structured way for individual buyers to access institutional-grade capital for local acquisitions without the rigid constraints of a commercial mortgage.
The Cost of Capital in Leeds
Interest rates define your margin. In 2026, unsecured business loans from major UK banks range from 9.94% to 15.73% APR. Secured debt is cheaper but requires assets. Bringing in equity investors eliminates the burden of monthly interest. However, it introduces equity dilution. You trade a percentage of future profits for current liquidity. For those looking at other regional hubs, our guide on acquisition funding Bristol provides a useful benchmark for southern market pricing. You can also explore the UK Government Business Finance and Support portal to find regional schemes that might lower your overall cost.
Speed to Close: Which Funding is Fastest?
Deal fatigue kills transactions. Traditional banks often require three to six months for approval. This delay can alienate sellers. Alternative lenders can provide term sheets in days and close within weeks. This speed is a competitive advantage in the Leeds mid-market. Mezzanine finance is a hybrid of debt and equity that sits behind senior debt in the repayment queue, typically used to fund the gap between bank lending and the buyer's equity in mid-market Leeds transactions. It is more expensive than senior debt but less dilutive than pure equity.
The most common objection to acquisition funding Leeds is the cost of debt. High interest rates in 2026 make traditional borrowing feel prohibitive. This is a narrow view. Debt is a lever. If the target business yields a 20% return on capital and your debt costs 12%, the spread creates value. Leverage amplifies your internal rate of return (IRR). Your focus should remain on the yield of the target rather than the nominal cost of the capital. If the ROI exceeds the interest, the debt is working for you.
Preparing Your Leeds Acquisition for Funding Approval
Lenders fund structures, not just stories. In the Leeds market, your preparation must be forensic. A professional business valuation report is the baseline. It removes subjectivity. Lenders don't gamble on unverified numbers. They require a clear, defensible logic for the purchase price. Without a verified valuation, your funding application is speculative.
Securing acquisition funding Leeds depends on a high-quality "Funding Pack." This is a technical dossier. Clean bookkeeping is a non-negotiable requirement. If the target's financials are opaque, the funding process stops. Use the SellAnyBiz.com AI Builder to professionalise your outreach. It generates structured teasers and Information Memorandums. It turns raw operational data into a bankable narrative that institutional lenders respect.
The Essential Funding Pack Checklist
Lenders require continuity. You need three years of historical accounts. You also need 2026 year-to-date management figures. These figures prove current performance. Detailed cash flow forecasts are equally critical. They must reflect the 3.75% base rate and the 25% corporate tax rate. Precision is your best leverage. For a deeper look at valuation accuracy, review our guide on How to Value a Business in 2026.
Presenting the Deal to Lenders
Highlight the target's stability within the West Yorkshire economy. Focus on regional advantages. If the business has a localised supply chain or a dominant market share in Leeds, specify it. Address risks early. Customer concentration. Lease renewals. Recruitment hurdles. Proactive disclosure builds credibility. It shows you understand the operational reality of the business and have planned for friction.
Management of the review process is the final step. Use the SellAnyBiz.com secure data rooms. They provide a controlled, institutional-grade environment for lender due diligence. Emailing sensitive documents is a security risk. A structured data room is a professional standard. It speeds up approval. It signals that the deal is ready for completion. A well-prepared deal attracts better capital. Start preparing your Leeds acquisition today.
Accelerating Deal Completion with SellAnyBiz.com
Fragmented processes lead to deal fatigue. When discovery, due diligence, and funding are managed across disconnected tools, momentum stalls. SellAnyBiz.com provides the transaction infrastructure required to maintain deal velocity. The platform centralises every stage of the lifecycle. From initial interest to final completion. By housing the data room, communication logs, and task lists in one workspace, buyers reduce the friction that often kills mid-market transactions. In the competitive West Yorkshire market, this level of organisation is a differentiator.
Securing acquisition funding Leeds requires transparency. Lenders and investors need confidence in the data. The SellAnyBiz.com workspace allows for role-based collaboration. You can invite lawyers, accountants, and lenders into a secure environment. They access only what is necessary. This structured access professionalises the review process. It allows lenders to move through due diligence faster. It replaces messy email chains with a single source of truth. Precision in deal management leads to faster capital injection.
One Platform for the Entire Transaction
Successful buyers move from discovery to the data room without switching tools. SellAnyBiz.com facilitates this transition. You find a target. You execute a digital NDA. You gain controlled access to sensitive documents. The platform also supports funding introductions through its partner network. This ecosystem connects qualified buyers with capital providers who understand the Leeds manufacturing and tech sectors. You can explore the SellAnyBiz.com platform to see how these tools integrate into your acquisition strategy.
Professionalising the Buyer Mandate
Funding follows intent. A clear, professional buyer mandate signals that you are a serious participant. On SellAnyBiz.com, creating a mandate is a structured process. It defines your acquisition criteria. It outlines your sector focus in West Yorkshire. A well-crafted mandate attracts better funding offers because it demonstrates preparation. Lenders see a buyer who has defined their target and understands the risks.
Confidentiality remains the priority. Digital NDAs are integrated into the workflow. Access to the data room is tracked and controlled. This security protects the target business while giving you the tools to manage the transaction with institutional-grade discipline. Managing task lists from the LOI through to the final purchase agreement ensures no detail is overlooked. Professionalise your search. Find your next Leeds acquisition opportunity on SellAnyBiz.com.
Securing Your Position in the Leeds Market
Success in the West Yorkshire market requires more than intent. It requires a disciplined approach to the capital stack. We've explored how seller financing bridges valuation gaps and why alternative lenders outpace traditional banks in speed. Securing acquisition funding Leeds in 2026 relies on a foundation of verified data and professional transaction management. Structure dictates survival; preparation dictates terms. Your ability to present a bankable deal is your primary competitive advantage.
SellAnyBiz.com provides the transaction infrastructure to execute these complex deals. Our platform reflects 15+ years of transaction expertise. It offers AI-powered transaction workspaces and secure data rooms for lenders. You can manage every stage from LOI to completion within a single, structured environment. The tools are ready. The opportunities are verified. The process is now yours to command.
The Leeds economy remains resilient for those who arrive prepared. Use the right framework to turn a target into a closed deal. Browse Leeds business listings and start your acquisition journey today. Move forward with confidence.
Frequently Asked Questions
How much deposit do I need for a business acquisition in Leeds?
Most commercial lenders require a cash contribution between 20% and 40% of the total purchase price. This equity stake demonstrates your commitment to the transaction and reduces the lender's risk. For businesses with significant physical assets, such as manufacturing plants in West Yorkshire, you might secure higher leverage. Service-based firms often require a larger deposit. Having a verified valuation helps justify the loan-to-value ratio to your chosen bank.
Can I use a government grant to buy an existing business in West Yorkshire?
Direct government grants for the purchase price of an existing business are exceptionally rare in the UK. Most public funding in the Leeds region focuses on post-acquisition growth, research and development, or job creation. You should instead look at government-backed loan schemes or regional support for specific sectors like green energy. While grants won't fund the acquisition itself, they can provide essential working capital once the deal has successfully closed.
Is seller financing common for Leeds-based retail or service businesses?
Seller financing is increasingly prevalent in the 2026 Leeds market. It is a strategic way to bridge the gap between a buyer's available cash and the seller's valuation. In retail and service sectors, sellers often agree to defer 10% to 30% of the purchase price over one to three years. This arrangement often functions as an earn-out, ensuring the seller remains motivated to support a smooth transition of operations.
What is the typical interest rate for acquisition funding in 2026?
Representative APRs for unsecured business loans currently range from 9.94% to 15.73% as of September 2026. The Bank of England base rate sits at 3.75%, which directly influences the cost of secured debt. If you are pursuing acquisition funding Leeds through a high-street bank, expect rates to be lower than alternative lenders, though criteria will be stricter. Government-backed Start Up Loans remain available at a fixed interest rate of 7.5%.
How long does it take to secure funding for a Leeds business purchase?
The timeline depends heavily on the type of lender you choose. Traditional high-street banks in Leeds typically require three to six months to complete their credit committee reviews and due diligence. In contrast, alternative lenders and specialist boutique firms can often provide a term sheet in days and close the funding within four weeks. Using a structured workspace to organise your documents will significantly accelerate these timelines by reducing back-and-forth queries.
What documents will a Leeds commercial lender ask for during due diligence?
Lenders require a comprehensive funding pack to assess risk. You must provide three years of certified historical accounts, 2026 year-to-date management figures, and detailed cash flow forecasts. They will also request a professional business valuation report and evidence of the target’s tax compliance. Providing these documents through a secure data room ensures the process remains confidential and professional, which builds essential confidence with the lender’s underwriting team.
Can SellAnyBiz.com help me find lenders for my Leeds acquisition?
SellAnyBiz.com facilitates acquisition funding Leeds through its partner network of lenders and financial advisors. While the platform does not provide direct capital lending, it offers the tools to prepare bankable transaction materials. You can use the AI Builder to generate professional teasers and Information Memorandums that meet institutional standards. This preparation ensures you are matched with the most appropriate funding sources for your specific sector and deal size.
Is it possible to buy a business in Leeds with no money down?
Buying a business with zero personal capital is theoretically possible but extremely difficult in the current credit environment. It usually requires a combination of high seller financing and asset-based lending against the company's existing machinery or receivables. Lenders almost always prefer to see "skin in the game" from the buyer. Without a cash contribution, you will likely face significantly higher interest rates and more restrictive loan covenants from alternative capital providers.
Disclaimer
Disclaimer: SellAnyBiz provides general business marketplace, brokerage and transaction-support information. Services may be subject to regional legal and regulatory requirements. Please review our Disclaimer & Compliance Notice for full details.